Customs Value No-Charge Shipments: Samples and Warranty Goods
Key Points
- Transaction value under 19 U.S.C. 1401a(b) requires a bona fide sale; goods shipped at no charge have no price paid or payable, so transaction value is unavailable.
- CBP then works through the statutory valuation hierarchy in order: identical merchandise, similar merchandise, deductive value, computed value, and fallback, never skipping a method without documented reason.
- Declaring a customs value of zero on a no-charge commercial shipment is almost always incorrect and can trigger a penalty or a CBP hold.
- Warranty replacements sent free of charge to a U.S. buyer are dutiable at their full customs value, not at zero, unless a specific Chapter 98 provision applies.
- Accurate valuation documentation, such as a prior sales invoice or manufacturer's price list, is essential before the merchandise arrives.
On this page
- What "no charge" means for customs valuation
- The statutory valuation hierarchy and how it applies
- Common no-charge shipment types and how each is valued
- Chapter 98 and returned goods: limited relief
- Documentation requirements and entry practice
- What importers should do
- Key references
When goods are shipped to the United States without a commercial charge, CBP cannot use transaction value because there is no price paid or payable between buyer and seller. Instead, the importer must apply the next applicable method in the statutory valuation order established by 19 U.S.C. 1401a. That means no-charge shipments, including product samples, warranty replacements, promotional goods, and gifts between businesses, must still be assigned a positive customs value at entry.
The links in this article go to the primary documents: the statutes, regulations, and official tariff schedule pages themselves. Read the source.
What "no charge" means for customs valuation
Customs value is not the same as the invoice price. Under U.S. law, customs value is the appraised value determined by CBP using a specific statutory method. The most common method, transaction value, is built on the concept of a sale: a transfer of goods from seller to buyer in exchange for a price paid or payable.
When goods move between parties at no charge, there is no sale in the legal sense. Common examples include:
- Product samples sent to a prospective buyer or distributor
- Warranty replacement units shipped at no cost under a service agreement
- Promotional merchandise sent to trade-show exhibitors or marketing partners
- Inter-company transfers of tooling, molds, or test equipment at no invoice price
- Gifts sent from a foreign company to a U.S. affiliate
- Repaired or refurbished goods returned to the owner without a separate charge for the goods themselves
In each case, transaction value fails at the threshold test in 19 U.S.C. 1401a(b), and the importer must move down the hierarchy.
The statutory valuation hierarchy and how it applies
The valuation statute sets out five alternative methods in a fixed sequence. An importer must use the first method for which sufficient information exists. A method may be skipped only when the information needed to apply it is genuinely unavailable, not merely inconvenient. The implementing regulation at 19 CFR 152.103 details how each method is applied in practice.
Step 1: Identical merchandise (19 U.S.C. 1401a(c))
CBP looks for a recent transaction value of identical merchandise exported to the United States at or about the same time and at the same commercial level. "Identical" means the same in all respects: physical characteristics, quality, and reputation. If the supplier sells the same item commercially to other U.S. buyers, that sales price is the starting point. An importer or broker should pull a recent commercial invoice for an identical sale and present it to support the declared value.
Step 2: Similar merchandise (19 U.S.C. 1401a(c))
If no identical item was sold, CBP considers merchandise that closely resembles the imported goods in materials, components, quality, and commercial interchangeability. The evidentiary standard is the same: a documented transaction value from a comparable sale.
Step 3: Deductive value (19 U.S.C. 1401a(d))
Deductive value works backward from the U.S. resale price of the imported merchandise or identical or similar goods. From that resale price, the importer subtracts commissions, general expenses, profit, transportation, insurance, and any duties and taxes. What remains is the deductive customs value. This method is useful when the goods are sold in the United States but no foreign transaction value is available.
Step 4: Computed value (19 U.S.C. 1401a(e))
Computed value builds the customs value from the foreign producer's cost of materials and fabrication, plus profit and general expenses equal to those typically seen among producers in the exporting country, plus packing costs. This method requires detailed cost data from the manufacturer, which the importer may not be able to obtain independently.
Step 5: Fallback value (19 U.S.C. 1401a(f))
When none of the preceding methods yields a value, the fallback method allows flexible application using criteria consistent with the General Agreement on Tariffs and Trade valuation principles. The fallback method cannot be based on arbitrary or fictitious values, U.S.-origin selling prices, minimum customs values, or values of merchandise exported from a country other than the country of export. A well-documented estimate tied to a manufacturer's list price, catalog price, or insurance value typically satisfies the fallback standard.
Common no-charge shipment types and how each is valued
Product samples
Samples shipped free of charge to evaluate quality or fit are among the most common no-charge imports. Because there is no sale, the importer typically uses the identical or similar merchandise method, relying on the supplier's commercial price list or a recent invoice for the same item. If the sample is genuinely unique and has no commercial equivalent, the fallback method applies, and the declared value is typically the manufacturing cost plus a reasonable profit margin supported by documentation from the supplier.
Warranty replacements
A warranty replacement is a new unit shipped to replace a defective one at no additional charge. The replacement is a dutiable importation. The customs value is the full commercial value of the replacement unit, not zero, because the no-charge nature of the shipment reflects the terms of a service agreement rather than the value of the goods themselves. The correct value is usually the identical or similar merchandise transaction value from ordinary commercial sales of that unit.
Some importers mistakenly believe a warranty replacement is duty-free because nothing was invoiced. CBP does not share that view. Duties, and any applicable Section 301 or Section 232 tariffs, apply to the appraised value of the goods regardless of whether the buyer paid for them.
Inter-company transfers and promotional goods
Goods transferred between a parent company and a subsidiary, or sent as promotional items, present the same valuation challenge. Related-party transfers may use transaction value only if the relationship did not influence the price, a standard that cannot be met when the price is zero. The hierarchy therefore applies. Catalog prices, transfer pricing studies, or the deductive method based on anticipated U.S. resale prices are common solutions.
Chapter 98 and returned goods: limited relief
The Harmonized Tariff Schedule's Chapter 98, accessible through the USITC HTS portal, contains several provisions that limit or eliminate duty on specific categories of returning goods. The most relevant for no-charge shipments include:
- U.S. goods returned: American-made goods exported and returned without having been advanced in value or improved in condition abroad may qualify for duty-free treatment. The importer must establish U.S. origin and that no foreign processing occurred.
- Articles exported for repair or alteration: Goods sent abroad solely for repair, alteration, or processing and returned to the same owner are eligible for a reduced duty rate applied only to the value of the repair or alteration, not the full value of the article. This provision does not eliminate duty entirely, but it can significantly reduce it. Full documentation of the exported condition, the repair performed, and the return shipment is required.
- Temporary exports: Items such as tools, molds, or professional equipment sent abroad temporarily and returned unchanged may qualify for duty-free entry under specific conditions.
Chapter 98 relief is narrow and conditional. It does not cover warranty replacements that are new units or samples that were manufactured abroad. Attempting to enter a no-charge foreign-manufactured product under a Chapter 98 heading without meeting its conditions is a valuation error that can result in penalties.
For context on how entry date and applicable tariff provisions interact with these valuation questions, see our article on why entry date changes the duty on a U.S. import.
Documentation requirements and entry practice
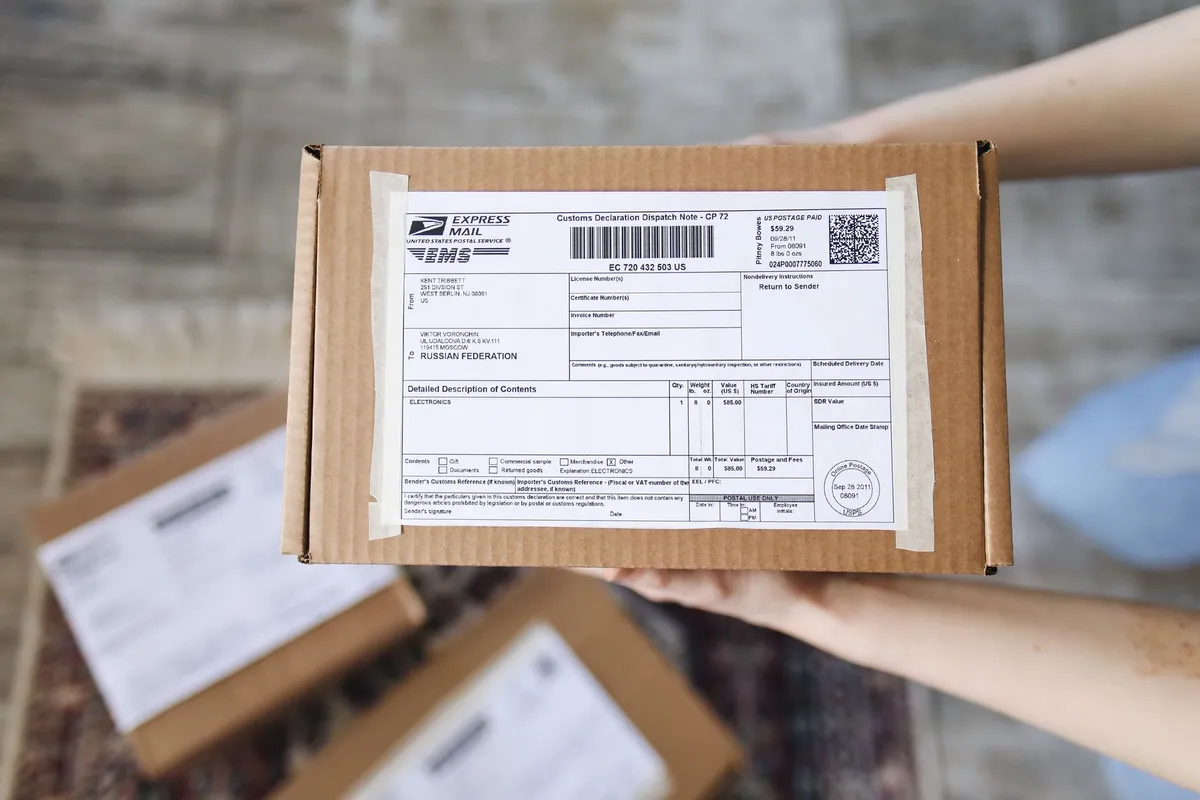
Proper documentation is the practical foundation of a defensible no-charge entry. Because the commercial invoice shows a zero price, the broker or importer must supply supplemental records that explain and support the declared customs value.
What to prepare before the goods arrive
- A supplier letter or affidavit explaining why the goods are being shipped at no charge (warranty, sample, promotional, etc.)
- A commercial price list, catalog, or recent invoice for identical or similar goods sold to unrelated U.S. buyers
- A manufacturer's cost breakdown if the fallback or computed value method will be used
- Correspondence documenting the warranty claim or sample request, to establish the commercial context
Entry paperwork
The commercial invoice accompanying a no-charge shipment should state the reason for the zero charge and include the fair market value or declared customs value prominently. CBP regulations at 19 CFR 152.103 govern the specific information importers must provide to support an alternative valuation method. Filing under the wrong value, or filing zero without a valid Chapter 98 basis, creates liability for underpayment of duties and potential penalties under the customs fraud and negligence statutes.
Marking and country of origin
No-charge status does not affect country-of-origin marking requirements. Every article of foreign origin entering the United States must be marked with its country of origin in a conspicuous place. Samples and promotional goods are not exempt.
What importers should do
- Before shipping any no-charge goods to the United States, identify which valuation method in the 19 U.S.C. 1401a hierarchy applies and gather the supporting documentation, price lists, invoices for identical goods, or cost breakdowns, before the entry is filed.
- Review whether a Chapter 98 provision applies to the specific shipment type; do not assume a no-charge or returning shipment is automatically duty-free without confirming the conditions in the HTS are met.
- Instruct your freight forwarder and customs broker in writing that the commercial invoice value is zero but the customs value is a stated positive figure, and provide the documentation to support it.
- Audit recurring no-charge shipment programs, such as standing warranty replacement arrangements, to confirm the valuation methodology is applied consistently across all entries.
Key references
- 19 U.S.C. 1401a: The U.S. customs valuation statute, covering transaction value (b), identical merchandise (c), similar merchandise (c), deductive value (d), computed value (e), and fallback (f).
- 19 CFR Part 152: CBP's implementing regulations on classification and appraisement of merchandise, including the procedural requirements for each valuation method.
- Harmonized Tariff Schedule of the United States (USITC): The official HTS, including Chapter 98 provisions for returned goods, repairs, and alterations.
- CBP Trade Compliance and Importer Resources (cbp.gov): CBP's portal for importer guidance, including valuation-related informed compliance publications.
Working through tariffs on real entries? Try the free duty calculator, then see plans for the full toolkit.